How to Receive International Payments in India
 By Suraj Rao11 min read
What You'll Learn
- Every way to get paid from abroad can cost you in three places: a transfer fee, an exchange-rate markup and a receiving fee, so compare the rupees that reach your bank, not the headline fee.
- Keep a FIRA (or e-FIRC) for every export payment and make sure the right purpose code is declared, because together they show the money was export income.
- Exports of services can be zero-rated for GST, and registered exporters usually file an LUT each financial year to export without paying IGST, so confirm the details with a chartered accountant.
If you're a freelancer or agency in India with clients abroad, sending the invoice is only half the job. The money has to cross a border, change currency and land in your Indian bank account, and each step can take a slice. Then you need the paperwork to show it was export income. Luckily, you now have more options than the bank wire alone.
This guide compares bank wires, PayPal, Stripe, Wise, Payoneer and Skydo on how they work, fees, speed and documents. It then covers FIRA, purpose codes, GST and LUT, which currency to invoice in, and ways to cut fees. For the client-side basics, such as who pays transfer fees and what goes on a cross-border invoice, see our guide on how to invoice international clients.
The three fees to compare
Almost every route charges in some mix of three ways:
- Transfer or processing fee: a fixed amount, a percentage, or both, for moving the money.
- Exchange-rate (FX) markup: the gap between the rate you get and the mid-market rate. It's often the biggest cost, and the hardest to see, because it's built into the rate.
- Receiving or withdrawal fee: charged when money lands or moves to your Indian bank. On a SWIFT wire, intermediary banks can also take a cut.
Some providers add GST on their fees or charge for the payment certificate. So the only fair comparison is the rupee amount that reaches your bank for the same invoice.
Worked example
Say you invoice a US client $2,000 and the mid-market rate is ₹88 to the dollar. These rates are made up to show the math.
- At the mid-market rate, $2,000 is worth ₹1,76,000.
- Provider A shows no fee but converts at ₹86.50. You receive ₹1,73,000, so the markup cost ₹3,000 (about 1.7%).
- Provider B converts at the mid-market rate but charges a flat $25. You receive $1,975 × 88 = ₹1,73,800, so the fee cost ₹2,200 (1.25%).
- On a $500 invoice, B's flat $25 is 5%, while A's markup is still about 1.7%.
Flat fees tend to suit large invoices, and percentages can win on small ones.
The main ways to receive international payments in India
Every provider detail below is as of November 2026, from each provider's own pages. Fees and rules change often, so confirm current fees on each provider's site before you choose.
| Option | How the client pays | Fee types to check | Payment certificate |
|---|---|---|---|
| Bank wire (SWIFT) | International transfer to your Indian bank | Sender and intermediary fees, your bank's FX spread | FIRA or e-FIRC from your bank |
| PayPal | PayPal balance or card | Percentage plus fixed fee, conversion markup | Digital FIRA download |
| Stripe | Card on a checkout page | Processing percentage, extra fee for conversion | Ask Stripe |
| Wise Business | Local transfer to account details in their currency | Conversion fee, fixed e-FIRC fee, GST on fees | e-FIRC by email |
| Payoneer | Local transfer to receiving account details | Receiving fee by currency, conversion margin | Digital FIRC at no cost |
| Skydo | Local transfer to account details in their currency | Flat fee by invoice size | FIRA on every payment |
Bank wire (SWIFT)
You give the client your bank's SWIFT code and account details, and they send an international transfer. It works with almost any client and suits large invoices.
The costs are spread out: the client's bank charges to send, intermediary banks may take a fee, and your bank converts at its own rate. Receiving can be cheap. HDFC Bank's remittance fee schedule, for example, lists inward remittance charges as nil as of November 2026, and says the sender should choose "OUR" to avoid intermediary deductions. The exchange-rate spread is where you usually pay, so ask your bank which rate it applies. Expect to declare a purpose code and to collect the remittance document for each payment.
PayPal
PayPal is easy for small clients who already have an account. On the Indian side, as of November 2026:
- Fees: PayPal India's seller fees list 4.40% plus a fixed fee on payments from outside India, plus a markup when currency is converted.
- No balance: because of Indian regulations, PayPal moves your balance to your bank account automatically every day.
- Purpose code: you must set a purpose code before you can withdraw.
- FIRA: PayPal's FIRA page describes a free weekly digital FIRA from February 2026, kept for the last 12 months.
The fee and markup add up on large invoices.
Stripe
Stripe lets clients pay by card. Stripe's India docs say, as of November 2026, that Stripe is invite only in India, that individual businesses aren't supported for international transactions, and that international services payments need the buyer's name, billing address, a description of the service and a purpose code. Stripe's India pricing lists a higher rate for cards issued outside India, plus 2% if currency is converted. Ask Stripe how you'll get FIRA for your payouts.
Wise Business
Wise gives you account details in some foreign currencies, so a client can pay you with a local transfer. Wise's help page for Indian businesses says, as of November 2026, that you pay a conversion fee that depends on the currency plus a small fixed fee for the e-FIRC, that GST applies on Wise's fees, that the e-FIRC is emailed a few days after the transfer, and that you pick a purpose code at setup. There are minimum and maximum amounts per transaction, and not every currency is open to every business. See Wise's India business pricing.
Payoneer
Payoneer is common with marketplace freelancers and also offers receiving account details in several currencies. As of November 2026, its India pricing page shows a receiving fee that varies by currency and payment type, and a margin when money is converted to rupees. Its pages give different figures for USD receipts, so check the fee in your account. Funds for India-based customers are withdrawn to your Indian bank automatically, and Payoneer's Digital FIRC service delivers FIRA documents from its partner bank at no cost.
Skydo and other newer services
Some newer services are built for Indian exporters of services: they give you foreign account details, convert to rupees and issue the paperwork. Skydo's page for consultants says, as of November 2026, that it converts at the mid-market rate and charges $19 up to $2,000, $29 from $2,001 to $10,000, and 0.3% above that, with a FIRA on every payment. Compare others in this space on the same three fees, the certificate and payout speed.
FIRA and FIRC: what they are and why you need them
When foreign money lands in your account, the bank that converts it records an inward remittance. Your proof is usually a FIRA (Foreign Inward Remittance Advice) or an e-FIRC (electronic Foreign Inward Remittance Certificate). ICICI Bank's trade FAQ explains that banks moved from paper FIRCs to advices for export collections, keeping FIRCs for cases such as FDI. People still say "FIRC" for both.
Keep one for every export payment. It shows the money came from abroad through a bank, the purpose code, the rupee amount and the rate used. Your chartered accountant will use them to support zero-rated GST treatment, any GST refund and your income tax records. Download each one as the payment arrives and file it with the invoice, because some providers only keep them for a limited time.
Purpose codes for export of services
A purpose code is a short RBI code that tells the bank why money is coming in. It should match what you sell. Common inward codes for service exporters, from bank lists such as DBS India's and HDFC Bank's, include:
| Code | Description | Typical work |
|---|---|---|
| P0802 | Software consultancy or implementation (other than those covered in SOFTEX form) | Development, IT consulting |
| P1006 | Business and management consultancy and public relations services | Strategy, operations, PR |
| P1007 | Advertising and trade fair services | Marketing, ad campaigns |
| P1008 | Research and development services | R&D projects |
Some software exports use a separate code that needs a SOFTEX form, so ask your bank or CA which applies. If a payment goes in under the wrong code, ask the bank or provider to correct it.
GST on export of services and the LUT
This is a high-level overview, not tax advice. Check GST and LUT questions with a chartered accountant.
Export of services. Under section 2(6) of the IGST Act, a supply is an export of services only if every condition is met, including: you're in India, the client and the place of supply are outside India, and you're paid in convertible foreign exchange or, where the RBI allows, in rupees. A CBIC circular from October 2023 explains when rupee receipts through certain repatriable accounts count.
Zero-rated supply. Exports of services are zero-rated under section 16 of the IGST Act. A registered exporter can either pay IGST and claim a refund, or export without paying IGST under a bond or Letter of Undertaking (LUT).
Filing an LUT. The GST portal's LUT FAQ says registered taxpayers making zero-rated supplies furnish the LUT in Form GST RFD-11 on the portal before making the supply. It's commonly filed at the start of each financial year. Under an LUT, Rule 46 of the CGST Rules requires an endorsement on the invoice:
SUPPLY MEANT FOR EXPORT UNDER BOND OR LETTER OF UNDERTAKING
WITHOUT PAYMENT OF INTEGRATED TAX
LUT ARN: [your LUT reference]   Financial year: [2026-27]
The ARN line is common practice, not part of the rule. Whether you need to register for GST at all depends on your turnover and setup, so ask your CA.
Payment time limits. RBI rules also limit how long you can wait to receive export proceeds, and they were revised in 2026 through new export and import regulations and later amendments. Check the current limit with your bank or CA, and don't let export invoices sit unpaid for months.
Invoice in USD, EUR, GBP or INR?
Our guide to invoicing international clients covers exchange-rate risk in general. For Indian exporters, a few points are specific:
- Foreign currency is the norm. Clients abroad expect to pay in their own currency, and the export rules are built around receiving foreign exchange.
- INR invoices aren't simpler. The client still has to convert, so payments can arrive short, and rupee receipts only count as export payments where the RBI allows.
- Match the invoice to your account. If you have EUR account details, invoice in EUR and put those details on the invoice, so the client pays locally.
To set a rate that covers fees and conversion, use our hourly rate guide or hourly rate calculator.
Tips to reduce fees on international payments
- Compare the rupees that land, using the same invoice in each provider's calculator.
- Give clients local account details. A local transfer usually costs the client less than a SWIFT wire, and is less likely to arrive short.
- Match the route to the size. Flat-fee services for big invoices, percentage-based ones for small, occasional payments.
- Ask wire clients to choose "OUR", and say so in your contract and on the invoice.
- Batch small invoices into one monthly invoice where clients agree, so fixed fees hit once. A retainer makes this natural.
- Build fees into your price, and ask for a deposit on large projects.
- Keep terms short and follow up. Net 15 leaves less time for rates to move than net 30, and a reminder before the due date helps clients schedule a cross-border payment. Our payment reminder email templates cover every stage.
Getting paid faster with Tristiks Grow
Tristiks Grow doesn't move money or connect to banks, Wise, Payoneer or Skydo, and it doesn't file GST or fetch FIRAs. It handles the invoicing side, which is where most delays start.
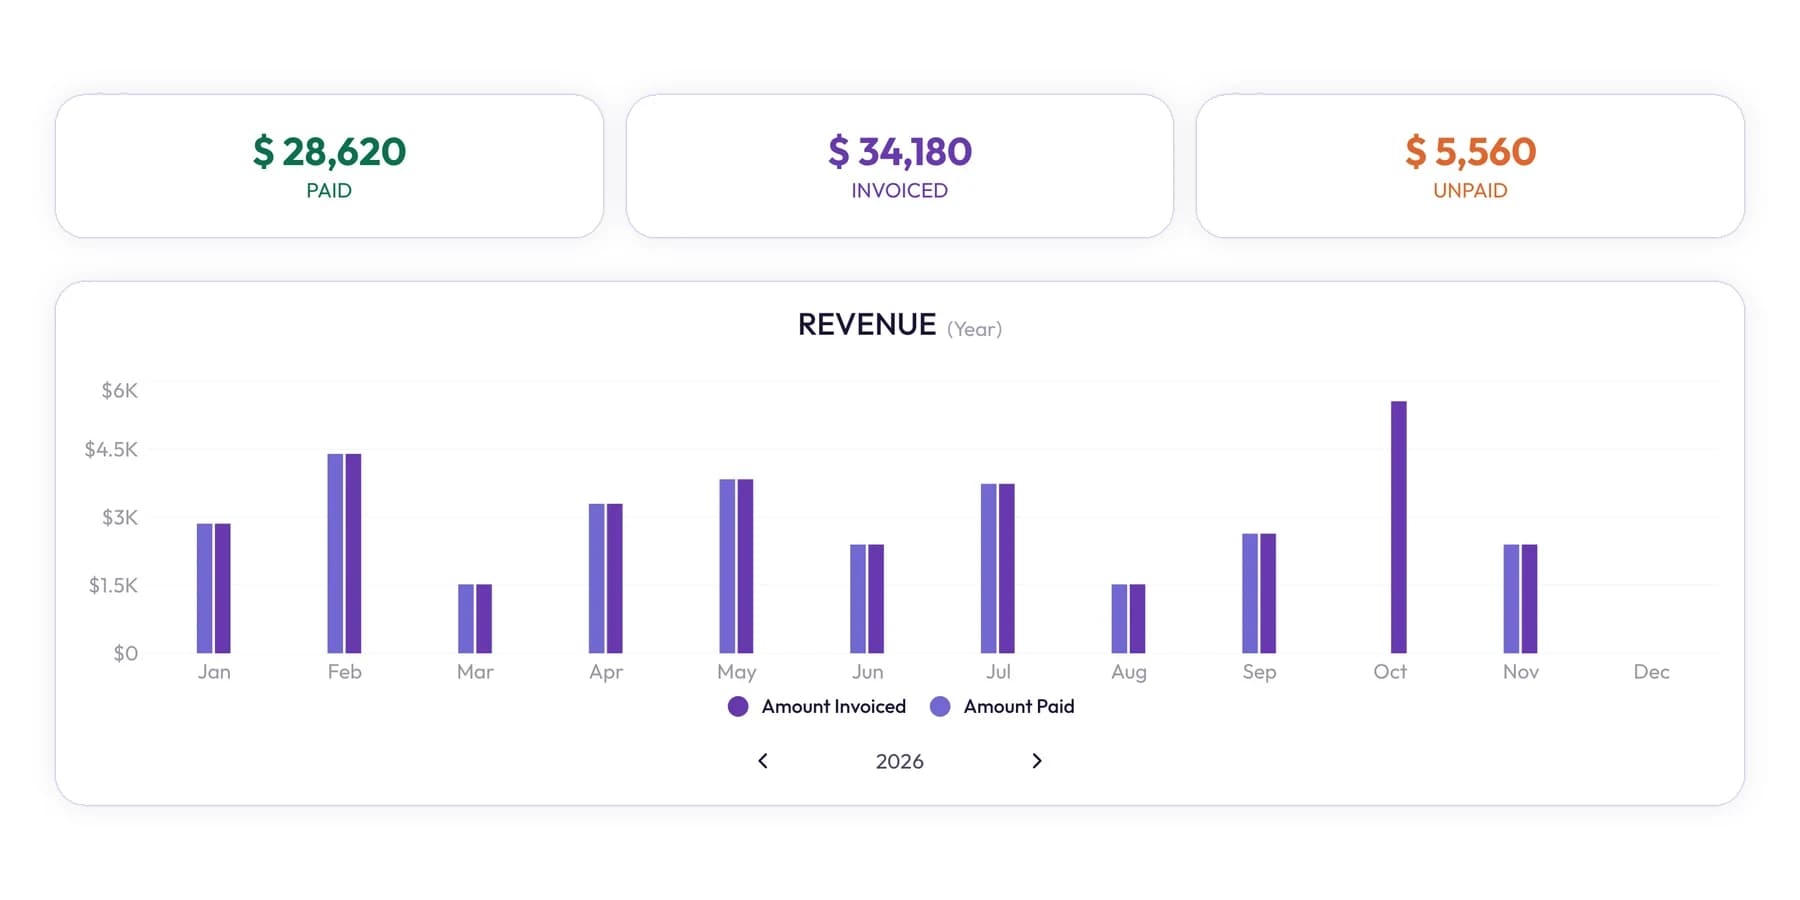
You save each client's currency, hourly rate, tax rate and payment terms on their client profile, then build invoices from tracked hours and expenses in that client's currency, with a note for your LUT endorsement and payment details. Each invoice goes out with a secure link where the client can view it and download the PDF, and you mark it paid in one click when the money arrives. Totals across clients show in the currency you choose, and reminders can email clients 3 days before the due date, on the day, and 7, 14 and 30 days after.
Card and PayPal payments on invoices are coming soon. Today, clients pay by bank transfer or whichever service you use, with your own payment details on the invoice. See the full flow on our invoicing software page.
Frequently asked questions
What is the cheapest way to receive international payments in India?
It depends on invoice size and currency. Local account details in the client's currency are often cheaper than a SWIFT wire or card payment, and flat-fee services tend to win on larger invoices. Compare the rupee amount each option delivers for your typical invoice.
Do I need a FIRA for every payment?
It's good practice to keep one for every export payment. It proves the money came from abroad for the declared purpose, and your CA will use it for GST and income tax. Most banks and providers issue them automatically or on request.
Do freelancers have to charge GST to foreign clients?
Exports of services that meet all the IGST Act conditions are zero-rated, so a registered exporter usually doesn't charge GST to the foreign client, either by filing an LUT or by paying IGST and claiming a refund. Whether you need to register depends on your situation, so check with a chartered accountant.
Which purpose code should I use as a freelancer?
Use the code that matches the service, such as P0802 for software consultancy or P1006 for business and management consultancy. If your work doesn't clearly fit, ask your bank or CA before the first payment arrives.
Wrap up
To keep more of every payment from abroad, compare providers on the full cost, declare the right purpose code, keep a FIRA for each payment and file your LUT before the year's first export invoice. Confirm current fees on each provider's site and check GST questions with a chartered accountant.
To invoice each client in their own currency, with your export details on every invoice and reminders that follow up for you, try Tristiks Grow invoicing free for 14 days, no card needed.
Category: Payments, Freelancing
Suraj Rao
Suraj Rao is the founder of Tristiks, the team behind Tristiks Grow and its desktop time tracker OneTrack. He writes about time tracking, client work and getting paid, and about DevOps, cloud and AI from years of building software.